Regarding investment avenues, Bank fixed deposits, and mutual funds are the best options for retail investors, but recurring deposits and SIP mutual funds are the best options if one wishes to invest in regular savings. Looking into the broader investment aspect, we will discover two separate instruments: debt and equity. When one invests in equity, the person gets the ownership, while debt is the lending of money wherein the investee will owe you money. If we talk about RD or SIP, then RD, also known as the recurring deposit, is purely a debt product where the Bank owes you the principal and the interest upon maturity as SIP, which is commonly known as a systematic investment plan, could be debt-based, equity-based or a combination of both of them. Both these instruments have their own importance, but they are suitable for different kinds of investors. To analyze the suitability, you first must know them in detail.
Key Highlights
- RD: A bank term deposit with fixed, risk-free returns, tenure from 6 months to 10 years. Best for short-term goals.
- SIP: A mutual fund plan that invests a fixed amount monthly or quarterly through an auto-debit mandate. Can be debt, equity or both.
- Risk: RD returns are fixed; SIP returns depend on the market and the fund you choose.
- Bottom line: Choose RD for safety and short timelines, SIP for long-term growth if you can handle market ups and downs.
What is a Recurring Deposit(RD)?
RD or recurring deposits is a scheme offered by the Bank. It is a term deposit scheme. RD is the best instrument for the one who can make regular deposits, and the account holder gets interest. This interest is much higher than one can get through a savings account in the Bank. It offers enough flexibility to pick the amount of your convenience that you can deposit every month and a duration of a minimum of 6 months and a maximum of 10 years. It is an ideal investment option for the short term.
What is a Systematic Investment Plan(SIP)?
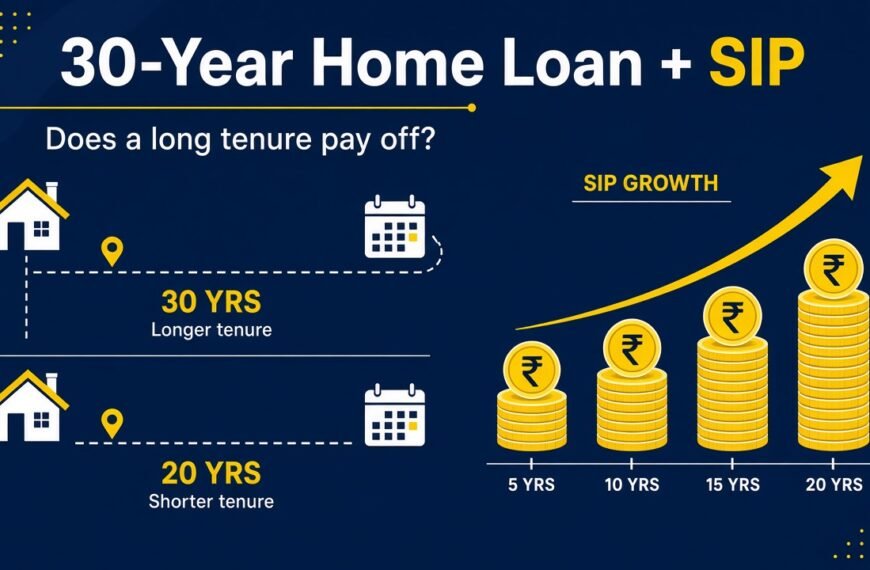
SIP or systematic investment plan falls under a mutual fund investment scheme where an investor invests a fixed amount in a particular scheme monthly or quarterly. To start a SIP, one must complete an application form and set up an auto-debit mandate (such as NACH or UPI AutoPay) with your bank. The mandate facilitates the automatic debit of the SIP amount from your account on a specific day of the month till you apply to stop it.
Difference between SIP and RD
The following table will help you understand the financial instruments clearly and let you know which is better – SIP or RD.
| Particular | Systematic investment plan | Recurring Deposit |
| Investment pattern | In SIP, individuals choose between the debt or equity based on their risk appetite and need to pay for it in every fixed interval of time such as quarterly or monthly. | RD is risk-free that why it is considered as safest mode of investment. |
| Risk factor | The returns depend upon the market situation and the fund that one has chosen. Debt funds usually carry lower risk and lower returns, while equity funds can offer higher returns with higher risk. | RD offers fixed returns. Bank deposits are insured by DICGC up to ₹5 lakh per depositor per bank. |
| Tenure | There is no fixed tenure for SIP; the investor can stop it at any point and redeem units (ELSS has a 3-year lock-in, and exit load may apply). | The tenure of a bank RD is usually 6 months to 10 years, depending on the bank; a Post Office RD runs for 5 years (60 monthly deposits) and can be closed early only after 3 years. Premature closure is usually allowed, with a penalty on the interest rate. |
| Returns | The interest rate is fixed in RD. For example, the Post Office 5-year RD pays 6.7% for October–December 2026. Bank RD rates vary by bank and tenure, and senior citizens usually get a higher rate. | Market-linked and not guaranteed; they depend on the fund and market conditions. |
| Liquidity | SIP offers liquidity on a condition of payment of exit load if the investor redeems the units before the particular period | Recurring deposit also offer liquidity but one need to pay pre-withdrawal charges if the person withdraws before the maturity. |
| Taxation | Interest earned on the RD is fully taxable at your slab rate | SIPs in ELSS funds qualify for deduction under section 123 (earlier 80C) only in the old tax regime. Gains on redeemed units are taxed as capital gains. |
Which one is better – SIP or RD?
The above table has given a clearer picture of the two investment instruments. Both have different benefits and vary in suitability, individual needs, and investment goals.
RD is suitable for investors who are reluctant to take risks and are capable enough to invest month every month. RD offers assured returns and facilitates both short-term and long-term goals. It is an ideal instrument that works as an emergency fund. As the returns are taxable, it suits those who fall under lower tax brackets. RD offers higher returns to senior citizens; hence, it benefits them.
SIP is more suitable for those willing to bear a risk to a certain extent. It is ideal for long-term investment goals. The best option with SIP is to opt for the scheme of his choice and switch units from one plan to another based on the risk appetite.
Bottom line
Both instruments have pros and cons; one must check their suitability before investing in any of these. The suitability could be analyzed by considering the income slab, risk-bearing capacity, investment goal, and regularity of earnings. If you are risk averse, you must opt for RD, but if you wish to get higher returns and can invest the money for the long term, then SIP is suitable for you.